

Work location policy remains in a state of flux. Metrigy’s Workplace Collaboration and Employee Experience 2027 global study of 403 organizations found that one-third require knowledge workers in the office full time, and those with hybrid policies require an average of 3.5 in-office days per week.
With mandates this common, attendance data such as badge swipes and desk occupancy might be expected to serve as the main yardstick for hybrid work. However, our research shows that attendance is a secondary measure for most organizations, and that the companies seeing the greatest results from collaboration technology rely more heavily on what employees tell them. The difference between counting people and understanding their experience is where IT and business leaders have the most room to improve how they evaluate work location strategies.
Attendance Is One Measure Among Several
When asked how they evaluate the success of their remote or hybrid work strategy, research participants most often cite cost savings and employee surveys, each named by more than half. About half track employee turnover, while roughly one-third (35.7%) use in-office attendance, placing it near the bottom of the list alongside environmental metrics. Very few organizations don’t actively evaluate their strategy at all.
Attendance data supports real-estate planning and helps justify investment in meeting rooms and reservation software. However, it shows where people work rather than how well they work or whether they plan to stay. Among organizations that require office time, the most common reasons are better informal collaboration and higher productivity, each cited by about half, and neither outcome shows up in an attendance report.
Successful Organizations Ask Their Employees
Metrigy’s Success Group for this study consists of the 95 organizations reporting above-average gains in productivity, cost reduction, and employee satisfaction from workplace collaboration technology investments. These organizations use employee surveys to evaluate hybrid work far more often than others, at 70.0% vs. 53.5% of the Non-Success Group, and they are also more likely to track environmental metrics.
The same pattern appears in how organizations measure their broader collaboration strategy. Employee feedback is the most common success measure overall, and the Success Group uses it at about the same rate as everyone else. Where successful organizations differ is in adding direct evidence of results, measuring productivity gains at 53.2% vs. 41.3% of others and tracking business process improvements more often.
This emphasis on employee input doesn’t mean successful organizations are moving away from the office. Those that require office time are the most convinced that the office raises productivity, and more than half of the Success Group expects its office space to grow in 2027. They also give employees more choice, with 34.0% operating fully flexible policies vs. 20.1% of others.
Formal Engagement Measurement Is Spreading
Just over half of organizations have a formal approach to measuring employee job satisfaction and engagement, and many more plan to implement one by the end of 2027. Adoption rises with company size, from fewer than half of small organizations (fewer than 250 employees) to most mid-size firms (between 250 and 2,500 employees).
Almost no Success Group organizations rule it out, while a small share of the Non-Success Group has no plans. Successful organizations also involve HR in collaboration technology decisions more often than the Non-Success Group, which may help connect engagement findings to the tools employees use every day.
Employee Experience Platforms Provide the Channel
Measuring engagement at scale depends on a consistent way to reach a distributed workforce. Our research shows that about half of organizations use employee experience platforms designed for community building and company-wide information sharing, and roughly one-fifth more plan to deploy one by the end of 2027.
The Success Group leads adoption, with nearly two-thirds using one compared with fewer than half of others, and no Success Group organization reports having no plans to adopt one. These platforms aren’t engagement measurement tools in themselves, but they provide the ability to share information and gather input across office, hybrid, and remote employees in one place.
From Occupancy Reports to Employee Experience
The same difference shows up in how organizations use desk and room reservation software. Space utilization reporting is the top feature for the Non-Success Group and the only feature it uses more often than the Success Group. Successful organizations use more of the platform, led by the ability to sit near colleagues, and are nearly twice as likely to use healthy-workplace monitoring.
What IT and Business Leaders Should Do
For companies not already doing the following, Metrigy recommends:
- • Treat attendance as one input – Use badge and occupancy data for space planning and pair it with employee surveys and turnover data when evaluating whether a hybrid strategy is working.
- Formalize engagement measurement – Put a recurring, formal approach to measuring job satisfaction and engagement in place, with a defined owner and schedule, and involve HR alongside IT, as the Success Group more often does.
- Use an employee experience platform to close the loop – Evaluate whether your platform provides the ability to run pulse surveys and report back on what changed as a result, so employees see that their input leads to action.
- Get more from workplace data – Look beyond space utilization reports to reservation features that support the employee experience, such as sitting near colleagues and healthy-workplace monitoring.
- Measure outcomes directly – Add productivity gains and business process improvements to the collaboration scorecard, since these are the measures where the Success Group differs most from others.
Successfully evaluating hybrid work requires understanding where employees work, measuring how engaged and productive they are, and acting on what they report. Attendance data answers the first of those questions, and successful organizations ask their employees for the rest.
For more on the study, see https://www.metrigy.com/product/workplace-collaboration-and-employee-experience-2027/.
Two numbers from our latest research look, at first glance, like they can’t both be true. About two-thirds of companies (66.9%) say they’ll likely buy their next communications technology directly from the platform provider. Yet just over two-thirds (67.6%) say some type of channel partner, rather than the platform provider, delivers the greatest value to their company.
As it turns out, both findings hold up in Metrigy’s Buying Strategies for Communication Services 2026-27 global study of 202 companies in the U.S., Canada, the U.K., Germany, and France in August.
Direct Is Already the Default
Looking first at where companies buy today, a clear majority buy workplace collaboration directly from the platform provider, such as 8×8, Cisco, GoTo, Microsoft, RingCentral, Vonage, or Zoom. The rest are split roughly evenly between buying only through a partner and buying from both. Contact center is more contested, as direct leads by a narrower margin and partners play a role, alone or alongside the platform provider, in a noticeably larger share of purchases (44.4%). Direct contact center purchases go to providers such as 8×8, Cisco, Dialpad, Five9, Genesys, NiCE, RingCentral, UJET, Vonage, or Zoom.
Company size explains much of that split; the median size of company buying direct is far smaller than one buying only through partners, and companies buying from both are larger still. In fact, most direct buyers make their purchases on the provider’s website rather than through a salesperson. Smaller companies can often click “buy” and be done, while larger ones use more vendors, have more locations, and require more integrations, which is precisely where partners earn their keep.
The Next Purchase Leans Direct—Mostly
Looking ahead, two-thirds of companies say they’ll definitely or probably buy direct next time and only a small minority (14.1%) lean toward a partner. Few say they’ll definitely buy from a partner.
Over the past five years, more companies shifted toward buying direct vs. buying from partners. But among companies with more than 1,000 employees, more moved toward partners than toward direct. The companies leaning toward a partner for their next purchase are larger, too, with a median of 500 employees vs. just over 200 for those set on buying direct.
There’s also a sizable middle ground of companies (19.0%) with no preference at all for their next purchase. Those undecided buyers, along with the largest enterprises, are the channel’s real opportunity.
The Value Vote Tells a Different Story
So if buyers are heading direct, why do partners keep coming out ahead on value? And why doesn’t that value translate into purchases?
When we asked which type of provider delivers the greatest value, the platform provider came out on top as the single most frequently chosen type, though its 32.4% share falls well short of a majority. The rest went to a long list of partner types: technology services distributors (TSDs), carriers, managed services providers (MSPs), systems integrators, cloud marketplaces, independent software vendors (ISVs), value-added resellers (VARs), and referral partners.
IT and CX leaders find value in the partner relationship for integration, migration, multi-vendor management, and maintenance, among other attributes. But they perceive leverage on product development with a direct relationship with the platform providers. There are dozens of vendors and thousands of partners to consider, resulting in more fragmentation among partners than platform providers. That fragmentation is the channel’s real problem, because while partners collectively deliver more value than platform providers, at buying time the smaller number of platform providers show up as big, familiar names and partners show up as thousands of smaller voices.
What Partners Deliver That Platforms Don’t
To find out why companies credit partners with so much value, we broke out the reasons behind each vote, and the answers split cleanly by provider type.
Companies that picked a partner type were more than twice as likely as those picking the platform provider to cite the ability to manage multiple vendors. They also gave more weight to geographic reach, local presence, and vertical industry expertise, which barely registered for the platform provider. On the flip side, companies that chose the platform provider leaned much harder on pricing and AI expertise, while integration capabilities ranked high for both groups.
That split explains a big reason for the apparent contradiction. , Buyers make the purchase decision on price and AI, where the platform provider looks strong and its website makes buying easy. Partners earn their value afterward—coordinating the vendors, locations, and integrations that no single platform provider covers. Not surprisingly, companies rank ongoing support as the biggest role partners play in their decisions, so the value is real, but it shows up after the purchase decision has already been made.
Waiting for the Value to Speak for Itself Isn’t a Strategy
Partners that want to improve their positioning should consider the following:
- Go after the undecided. A sizable group of buyers has no preference for their next purchase, so get in front of them before they land on a provider’s website.
- Put a number on multi-vendor management. If coordinating vendors is why customers value you, quantify what it saves them in staff hours and outages avoided, and lead with it in the sale, not at renewal.
- Focus on larger companies. Partner buyers are consistently bigger, and the largest enterprises are moving toward partners rather than away from them.
- Improve and promote AI expertise. Decision-makers are emphasizing companies that they consider to be AI specialists. Having and promoting that expertise is crucial.
For platform providers, the lesson cuts the other way, since direct momentum doesn’t mean partners matter less. Two-thirds of companies still say a partner delivers their greatest value, and partners are most involved in the larger, more complex accounts every provider wants. Treat partners as the ones who keep those customers running smoothly after the sale, not as a channel to route around.
For more information, check out the full study.
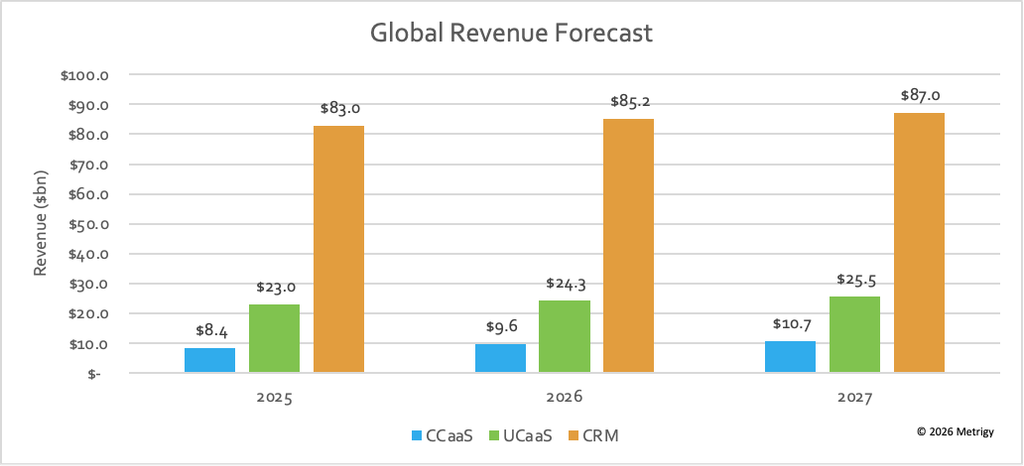
As we look toward 2027, the foundational markets Metrigy covers are progressing as forecasted with minimal change based on 1H26 actual numbers. Let’s break it down and how things could shift and change through 2027.
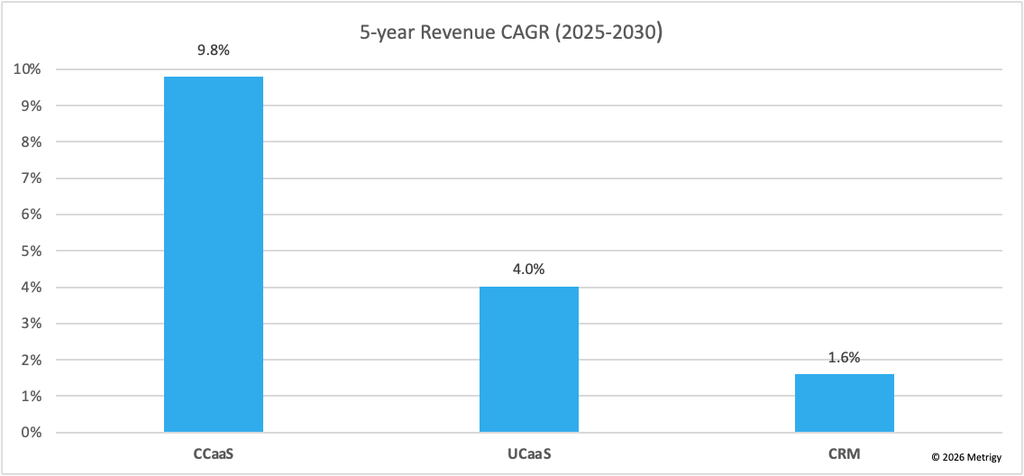
For CX, customer relationship management (CRM) is the largest market segment, on track to post $85.2 billion in 2026 revenue. On the flip side, contact center as a service (CCaaS) is the fastest growing market segment, albeit from the smallest base ($9.6 billion forecast for 2026).
While the CRM market is large, most companies that need a CRM system already have one so for providers to grow they need to be winning new business from competitors. Salesforce commands more than a quarter of the market. And the market is on track to continue growing at low single digits off a large base. We expect the continued expansion and evolution of AI, as well as the shift of CRM vendors to a headless model, relying on other AI apps to interface with data, to blur the lines between CRM and other customer experience platforms like CCaaS.
Of all the segments we track, CCaaS currently has the largest adoption upside since human contact center agents still operate predominantly from on-premises systems and dedicated cloud platforms. According to our research, with more than 50% of human agents still to migrate over to CCaaS, plus AI capabilities that add to premium pricing, there is a long on-ramp to growth. The CCaaS market is the one area where the growth attached to AI is hard to fully forecast beyond three years because the evolution of AI is outpacing what we can fathom and what businesses can keep up with beyond 12-24 months.
The market share leaders in CCaaS continue to be NiCE, Genesys, and Five9. However, this market has a broad set of competitors and new entrants, such as Microsoft, Salesforce, and Zoom, are making strides every year.
For workplace collaboration, unified communications-as-a-service (UCaaS) growth is steady as businesses continue to migrate off on-premises PBX and dedicated cloud platforms, even though many are de-emphasizing traditional phone service for employee communications, focusing instead on video conferencing and chat services. AI has long been used to augment UC through transcription and translation, and continue to expand these capabilities with the integration of context beyond meetings into note takers. We do not anticipate AI upending the UCaaS market but rather continue to enhance capabilities.
UCaaS is forecast to grow to $25.5 billion in 2027. Microsoft is the global market share revenue leader followed by RingCentral and Zoom. The leadership should hold steady at the top with smaller companies prone to consolidation or acquisition.
When a familiar voice can’t be trusted, every call carries risk
Voice calls are essential to doing business, whether it’s banking, healthcare, government, customer service, employee support, or thousands of other engagements. Phone calls are also fundamental to staying connected. From the joy of engaging with a loved one to the pain of an accident or emergency.
Deepfake technology challenges the basic assumption behind all of those interactions…trust. Trust that the voice on the call belongs to the person it claims to represent.
Modern AI tools can use a small audio sample (from social media, a recorded call, YouTube, etc.) to reproduce a person’s voice, tone, and cadence. Attackers use that deepfake voice during a live call to deceive their intended victim.
Attackers use that deepfake voice during a live call to deceive their intended victim, impersonating executives, coworkers, and family members to exploit the trust people place in a familiar voice. They use that trust to gain access to corporate networks, execute fraudulent business transactions, or defraud the most vulnerable members of our community.
Download and read this issue paper at ribboncommunications.com.
AI-driven vishing against communications platforms gives attackers access to a variety of enterprise resources. CISOs should proactively work with UC teams to enhance security.
Vishing, in which an attacker uses voice calls to gain access to company or personal information, is on the rise. Vishing attacks grew by a whopping 442% in 2024 alone, according to CrowdStrike. They are also growing more sophisticated as AI enables voice deepfakes to impersonate customers and employees and engage in social engineering attacks.
Protecting against vishing attacks is increasingly top of mind for those responsible for enterprise communications platforms, according to Metrigy’s “Workplace Collaboration Security and Compliance: 2027” global study of 403 organizations. Nearly 60% of respondents said they are adopting additional customer identity verification approaches to protect against vishing, and more than half are implementing security platforms specifically for that purpose.
What is vishing?
Continue reading at techtarget.com.
Metrigy’s global Workplace Collaboration and Employee Experience 2027 study of 403 organizations finds AI moving from pilot to practice, and the office growing, not shrinking.
November 3, 2026 – Research and advisory firm Metrigy released its Workplace Collaboration and Employee Experience 2027 research study, finding that AI is moving from pilot to practice across collaboration apps, phone systems, and meetings. Based on research with 403 organizations globally, the study finds that 40.8% already use AI assistants or copilots within their collaboration apps, and employee access to these assistants is expected to climb from 56.5% today to 73.0% by the end of 2027.
Agentic AI is following close behind. More than one-third of organizations (35.1%) already allow autonomous AI agents, and another 34.8% are evaluating them. Organizations seeing the greatest results from their collaboration investments are further ahead on nearly every AI measure, and they are twice as likely as their peers to allow autonomous agents.
AI is not the only shift underway. Despite years of debate over remote and hybrid work, the office is growing: 41.0% of organizations expect their office space to increase in 2027, compared to just 7.8% expecting a decrease. Investment is flowing into meeting rooms, with video, touch screens, and reservation software all set to expand by the end of 2027.
“AI is moving into the mainstream, and delivering measurable business value,” said Irwin Lazar, president and principal analyst at Metrigy and lead author of the study. “Organizations with the highest return on their workplace collaboration investments are deploying AI at a higher rate than others. IT and business leaders should ensure that they are positioned to leverage AI to improve collaboration and automate repeatable workflows.”
Workplace Collaboration and Employee Experience 2027 Highlights
Additional findings from the study include:
- AI receptionists are taking off – 34.6% of organizations use AI receptionists today, and another 22.3% plan to by the end of 2027—most often to handle after-hours inquiries and scheduling.
- Meeting rooms are getting smarter – Video-enabled meeting rooms will rise from 57.5% to 66.7% by the end of 2027, even as roughly two-thirds of office space remains devoted to individual work.
Despite the momentum, gaps remain. Nearly 42% of organizations lack AI for proactive management of their collaboration environment, and a similar share lack analytics—leaving room for improvement as AI spreads across the workplace.
Metrigy’s Workplace Collaboration and Employee Experience 2027 study examines how organizations are adopting AI, evolving the office, and investing in meetings, video, and calling technologies, and compares the practices of the most successful organizations with those of their peers.
The full report, including detailed findings, success-group analysis, and recommendations for technology and business leaders, is available for download to Metrigy clients or for individual purchase.
If you are interested in Metrigy’s Workplace Collaboration and Employee Experience 2027 study, please reach out to [email protected].
Media Contact:
Elly Hertz
Sr. Director of Content Marketing and Design, Metrigy
Phone: 877-638-7449 · Cell: 815-735-7059
Unified Communications as a Service (UCaaS): Hosted, multitenant service used for placing and receiving calls across the PSTN, sold on a per-seat subscription basis; aggregates telephony, presence, messaging/chat, collaboration, and meetings
What We Count
In this service, we count vendor’s and provider’s relative revenue in US$ recognized during the calendar year for every category. We do not include revenue from management systems, service, or support within individual product categories.
UCaaS seats: number of business users supported
Regions
- Worldwide: all areas of the world
- North America: U.S. and Canada
- EMEA: Europe, the Middle East, and Africa
- Asia-Pacific: Asia and the Pacific, including Japan and Australia
- CALA: Caribbean and Latin America, including Mexico
On-Prem PBX/UC Platforms: Proprietary system hardware and call control software, includes TDM, pure IP PBX, and hybrid TDM/IP systems
What We Count
In this service, we count vendor’s and provider’s relative revenue in US$ recognized during the calendar year for every category. We do not include revenue from management systems, service, or support within individual product categories.
PBX/UC licenses: number of unique users supported
Regions
- Worldwide: all areas of the world
- North America: U.S. and Canada
- EMEA: Europe, the Middle East, and Africa
- Asia-Pacific: Asia and the Pacific, including Japan and Australia
- CALA: Caribbean and Latin America, including Mexico
Enterprise SBC (eSBC): Network element that controls and manages real-time multimedia traffic flows between IP networks, handling signaling and media
What We Count
In this service, we count vendor’s and provider’s relative revenue in US$ recognized during the calendar year for every category. We do not include revenue from management systems, service, or support within individual product categories.
SBC sessions: number of simultaneous bi-directional media flows controlled via software licenses (not including oversubscription)
Regions
- Worldwide: all areas of the world
- North America: U.S. and Canada
- EMEA: Europe, the Middle East, and Africa
- Asia-Pacific: Asia and the Pacific, including Japan and Australia
- CALA: Caribbean and Latin America, including Mexico


